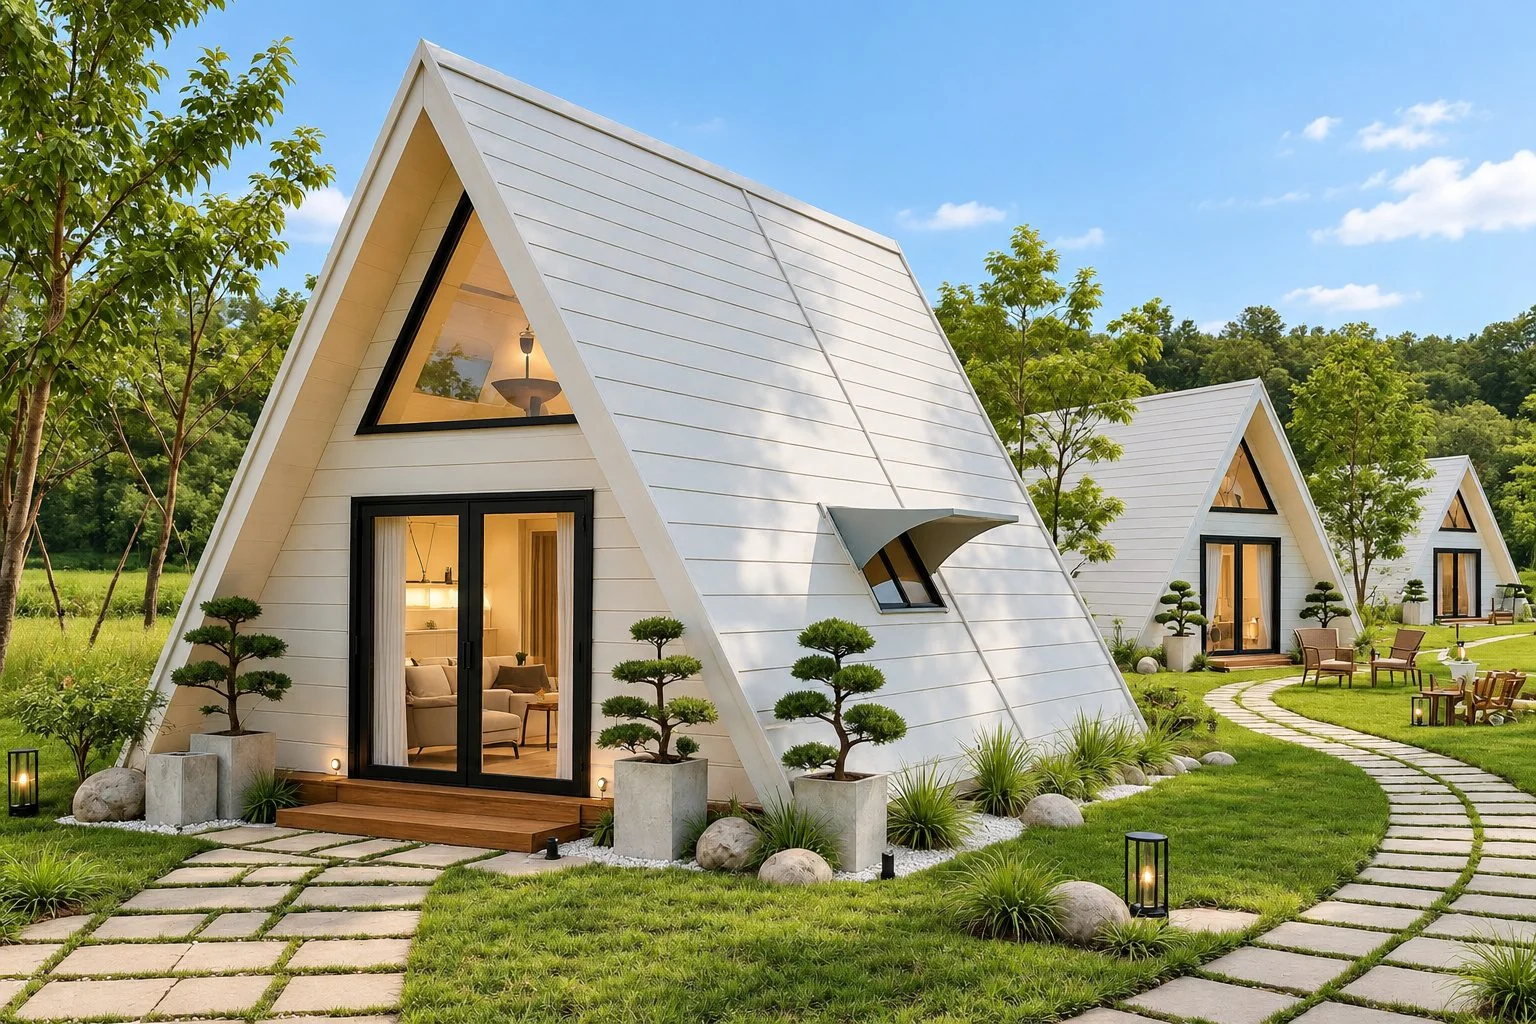
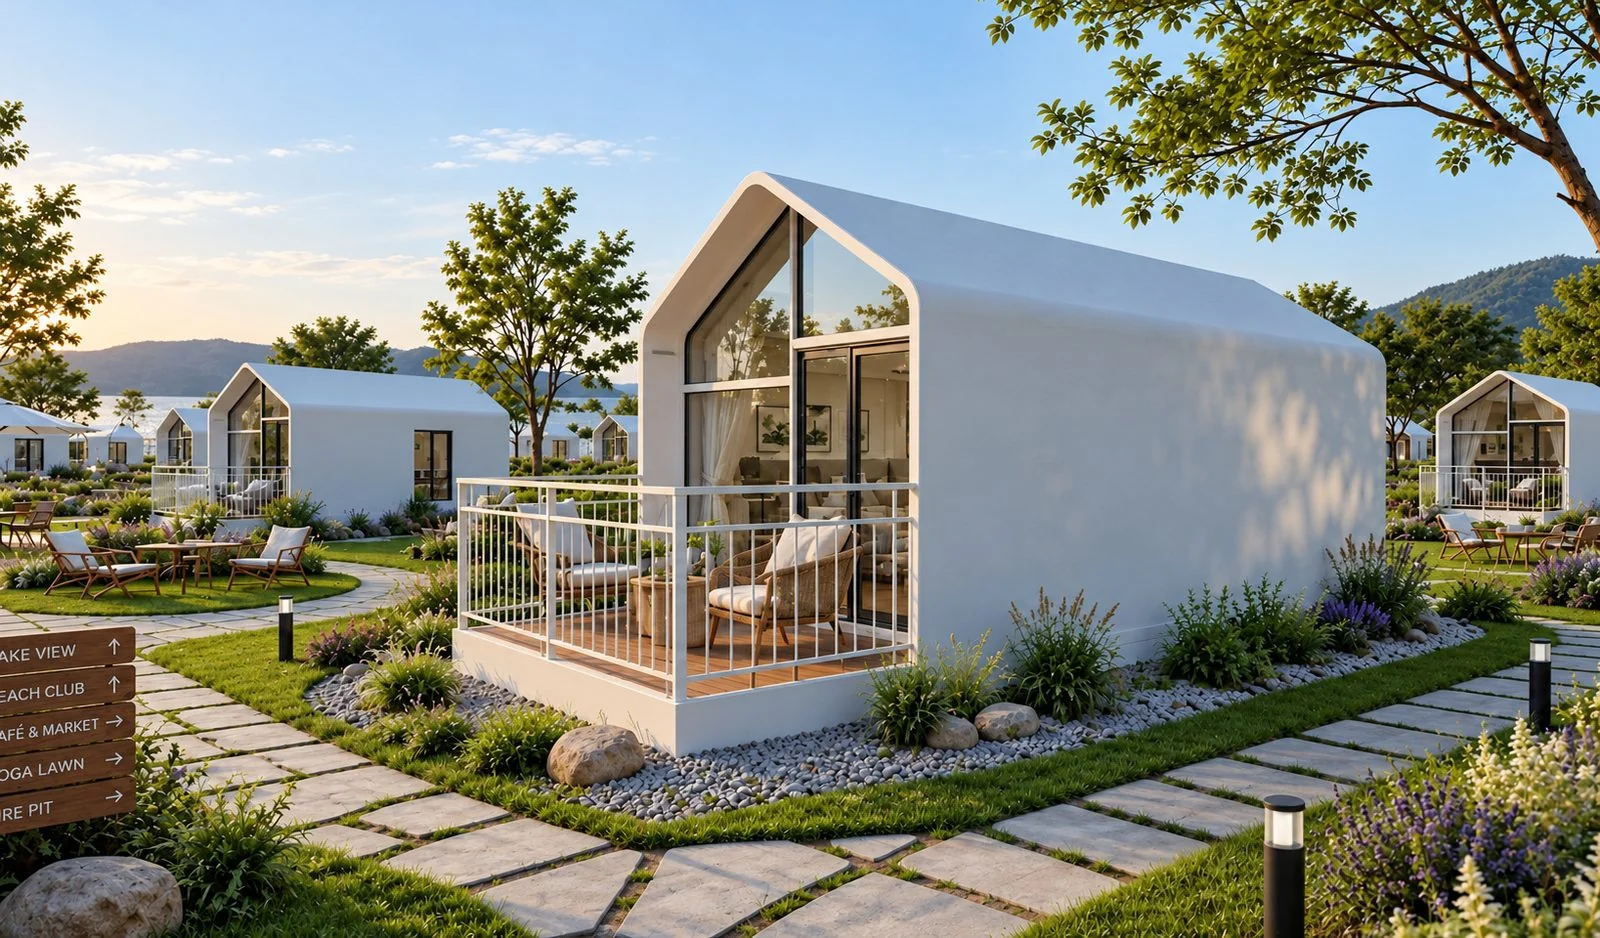
Outdoor hospitality and campsites
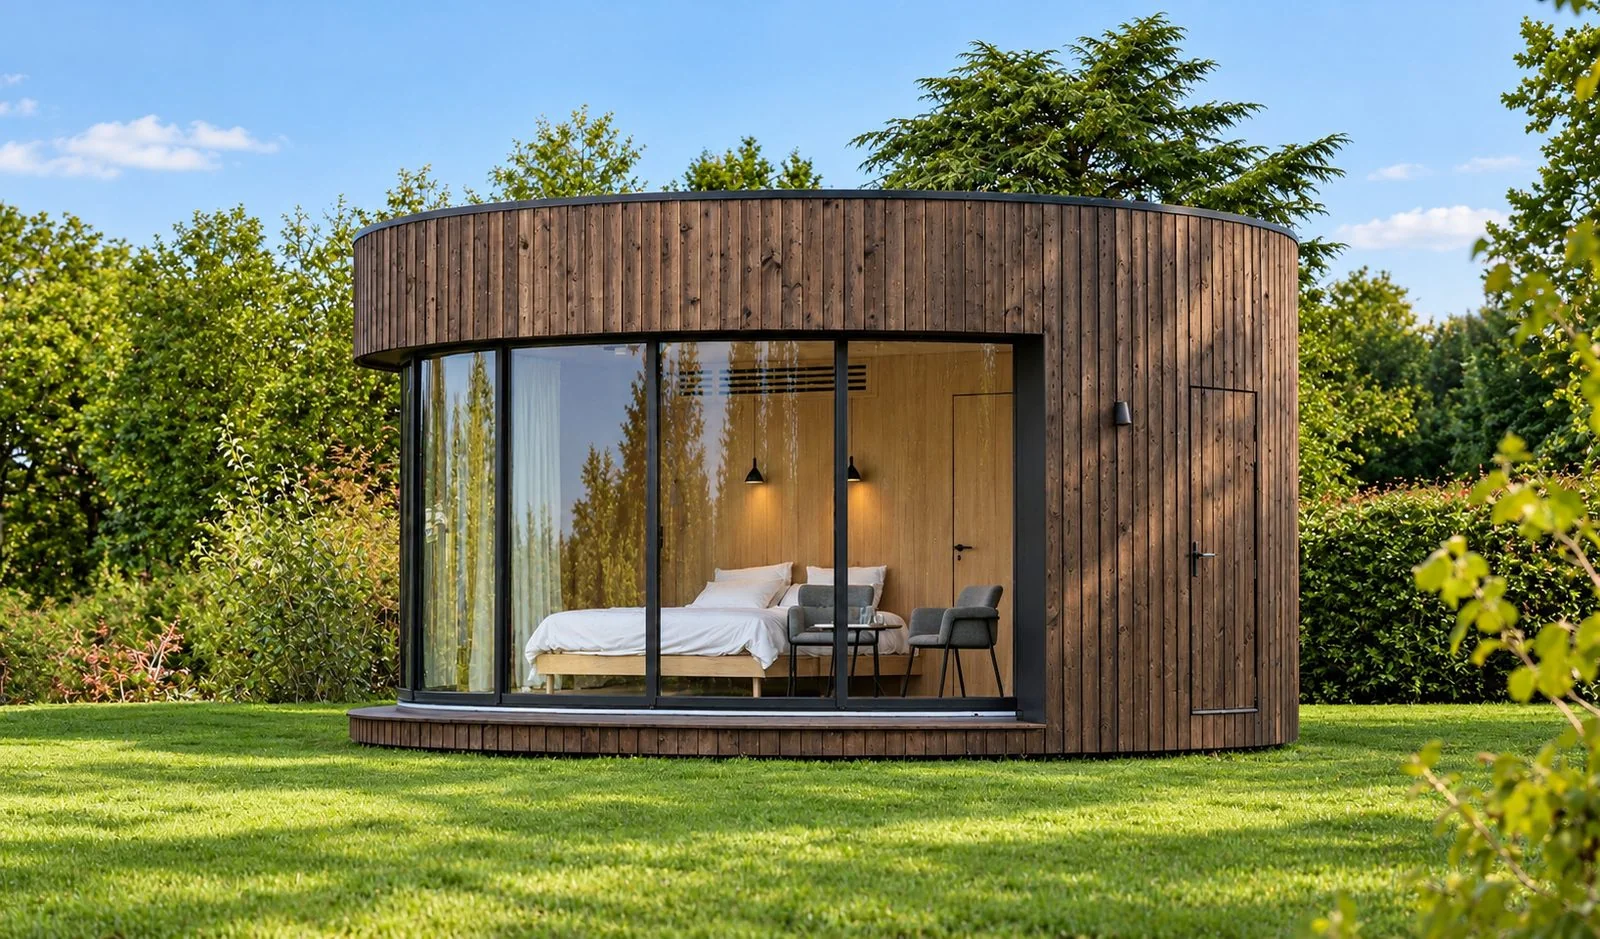
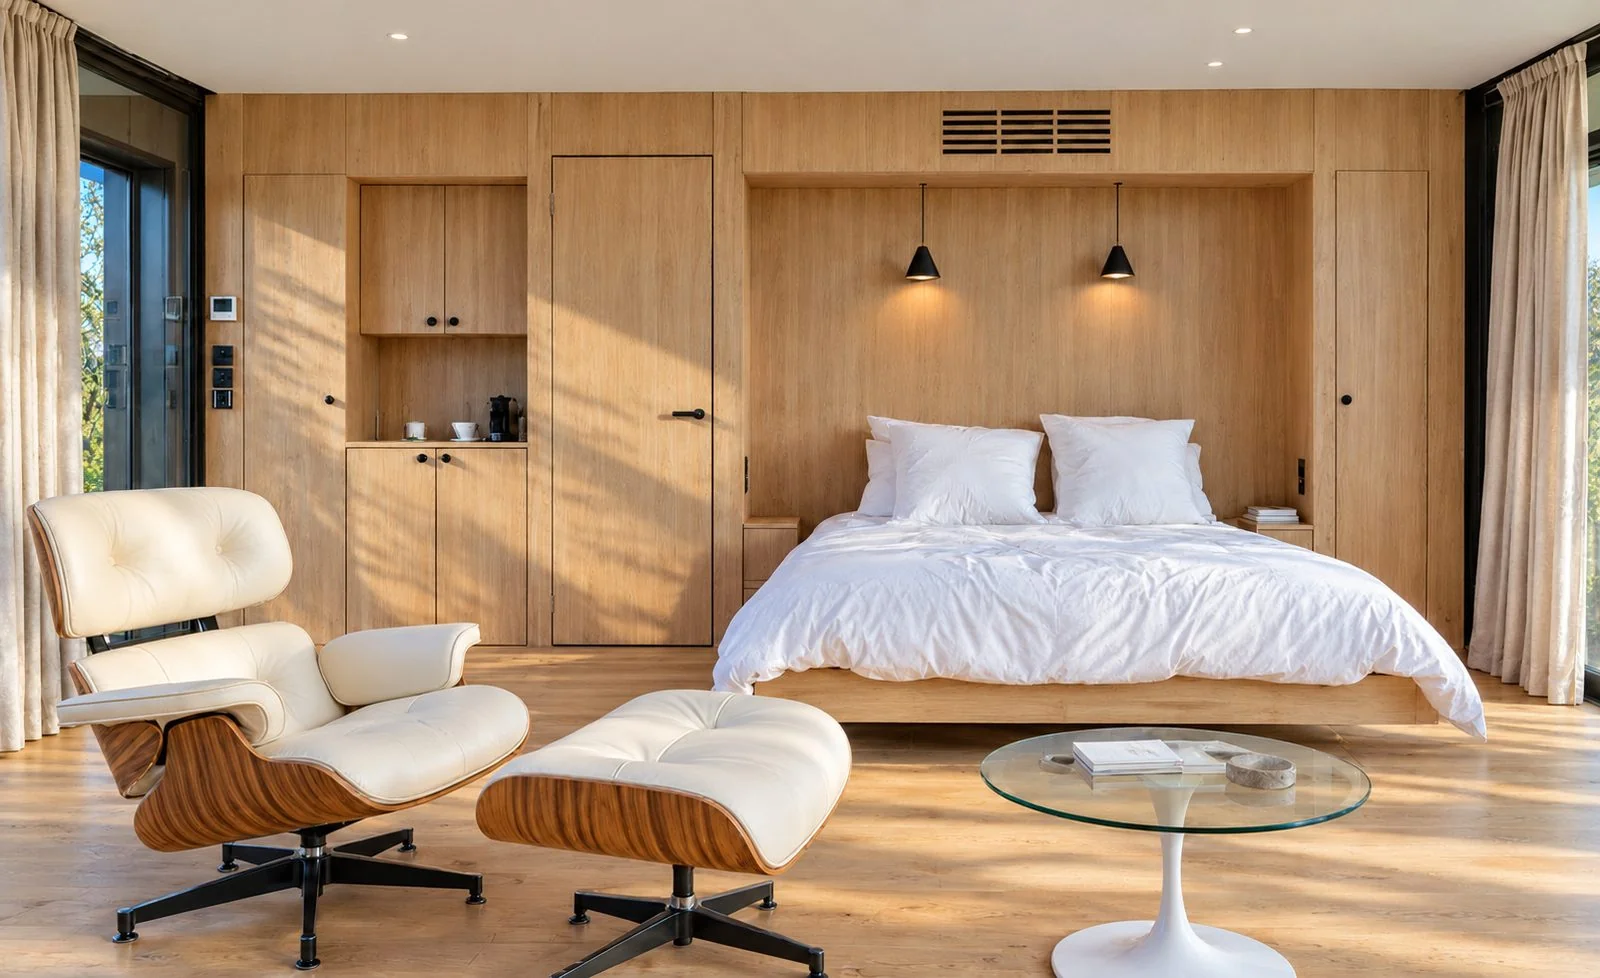
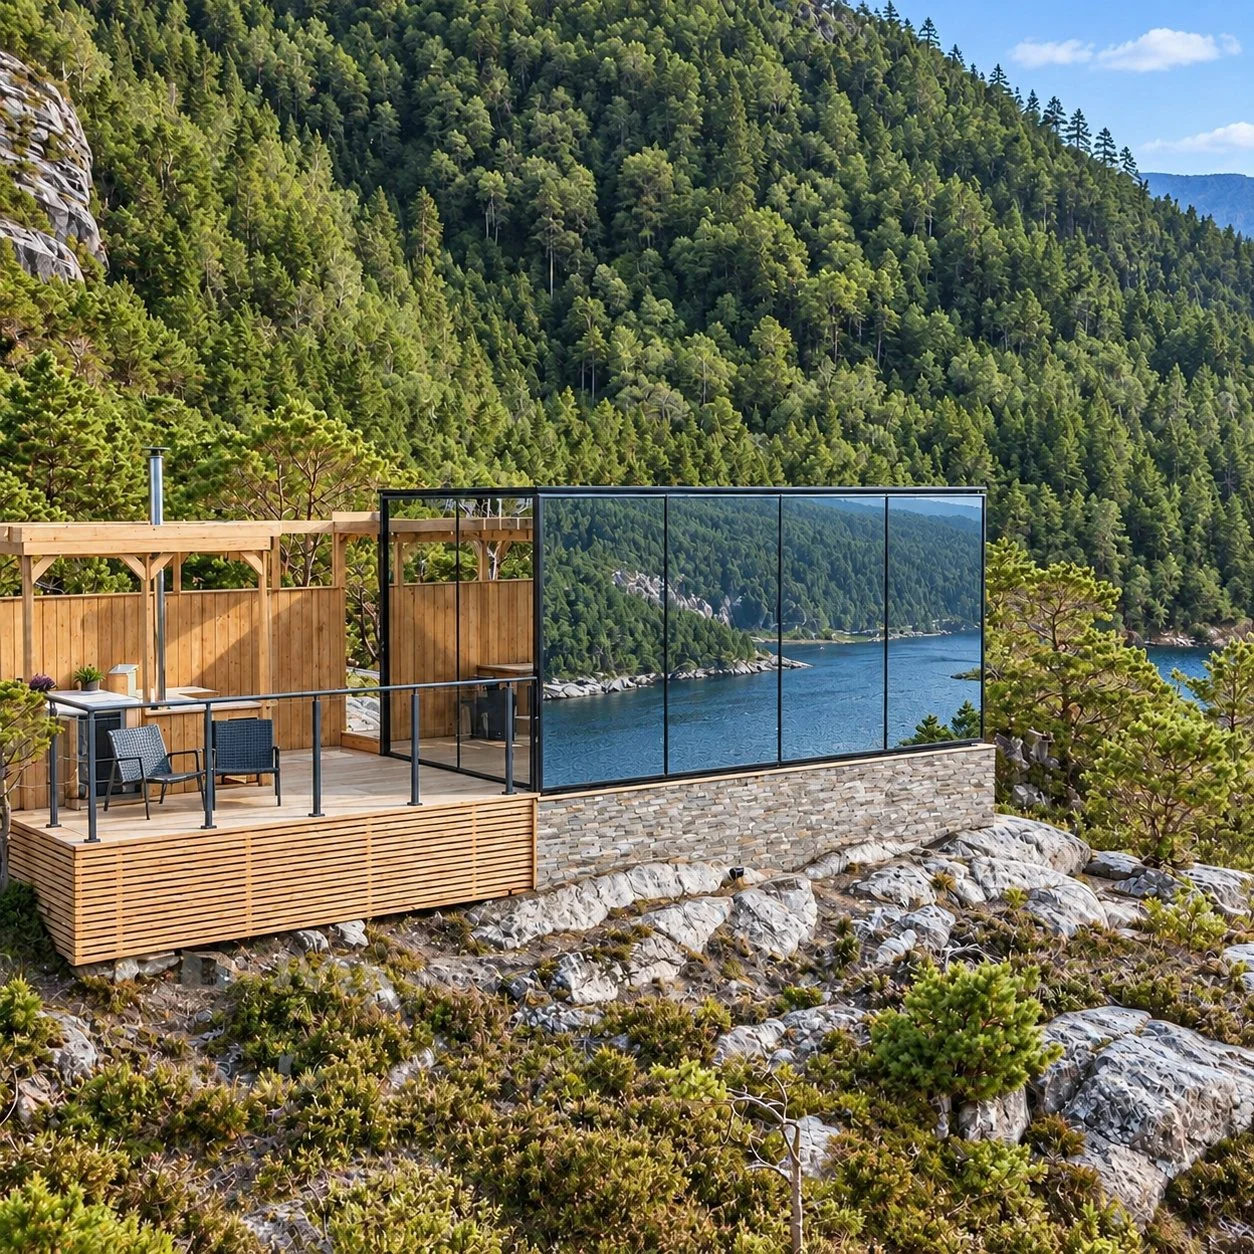
Premium accommodation, lodges, tiny houses, sanitary or wellness facilities.
Premium accommodation, lodges, tiny houses, sanitary or wellness facilities.
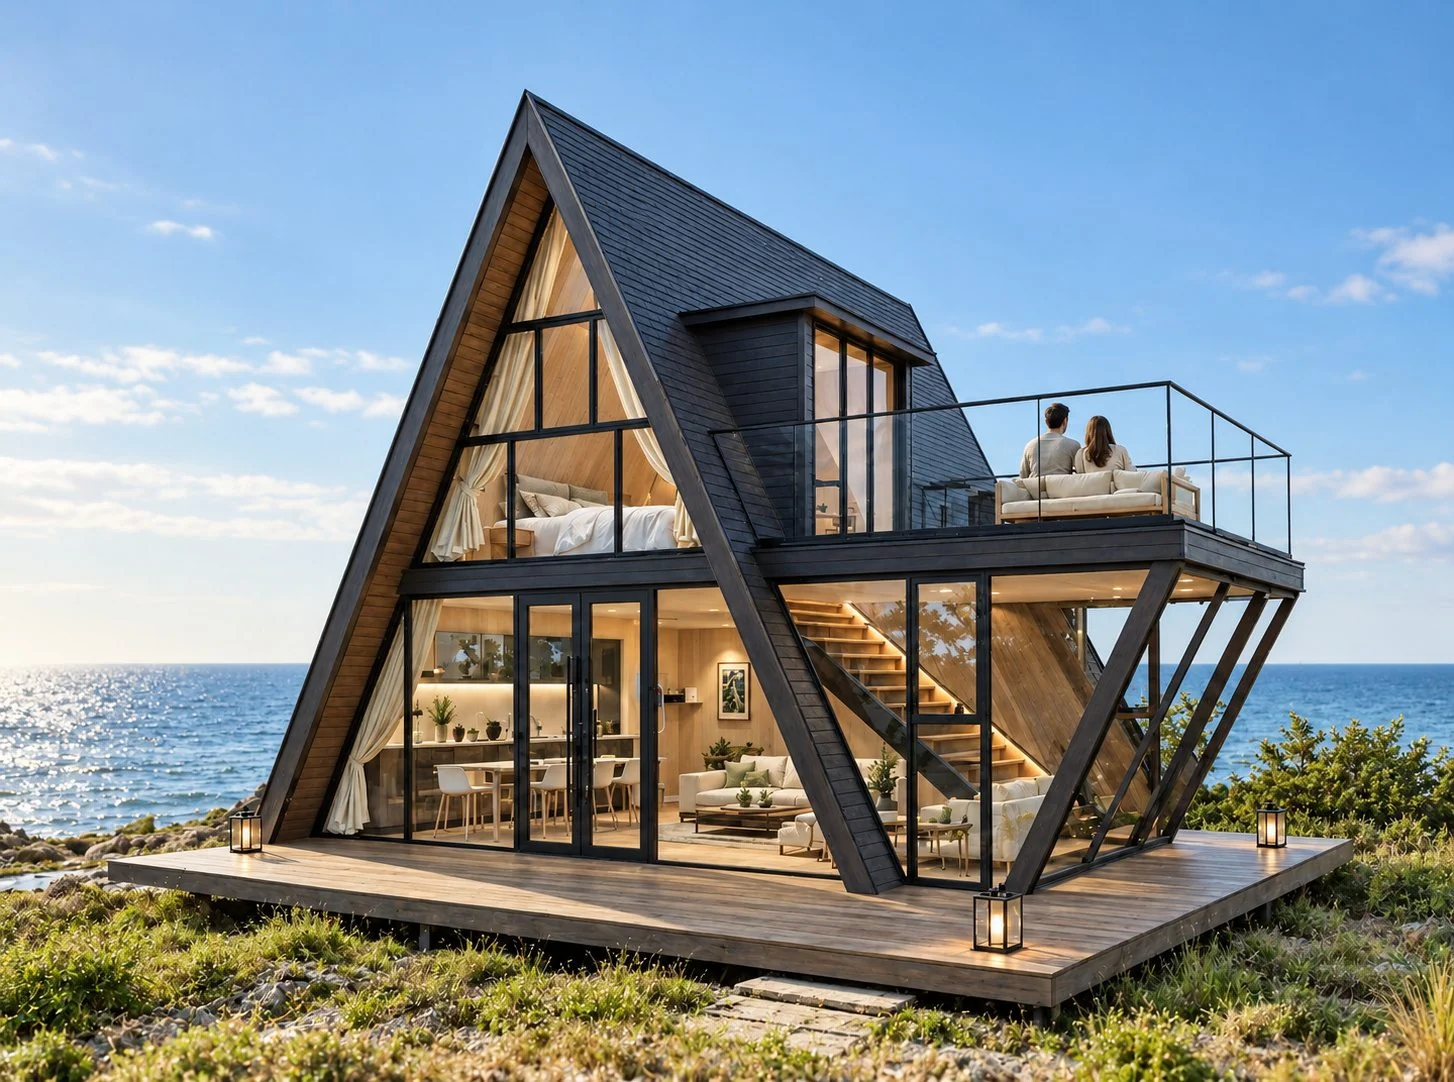
Capacity extensions, standalone suites, wellness spaces, high-end villas.
Modular offices, meeting rooms, coworking or reception spaces.
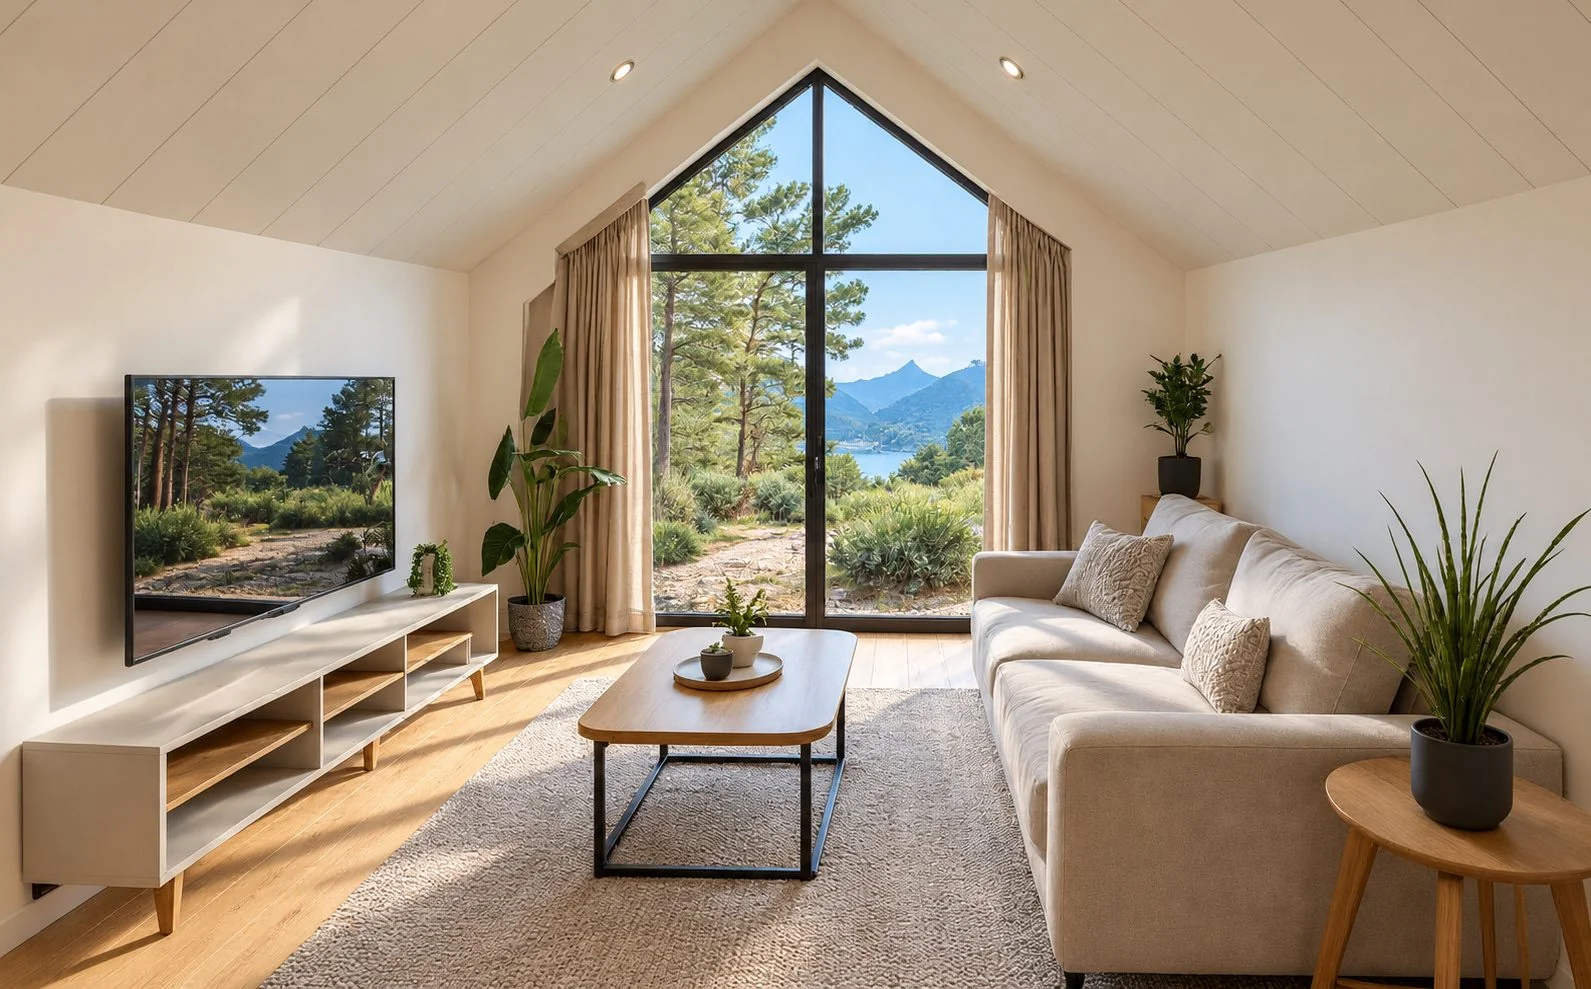
Temporary or permanent accommodation for your teams.
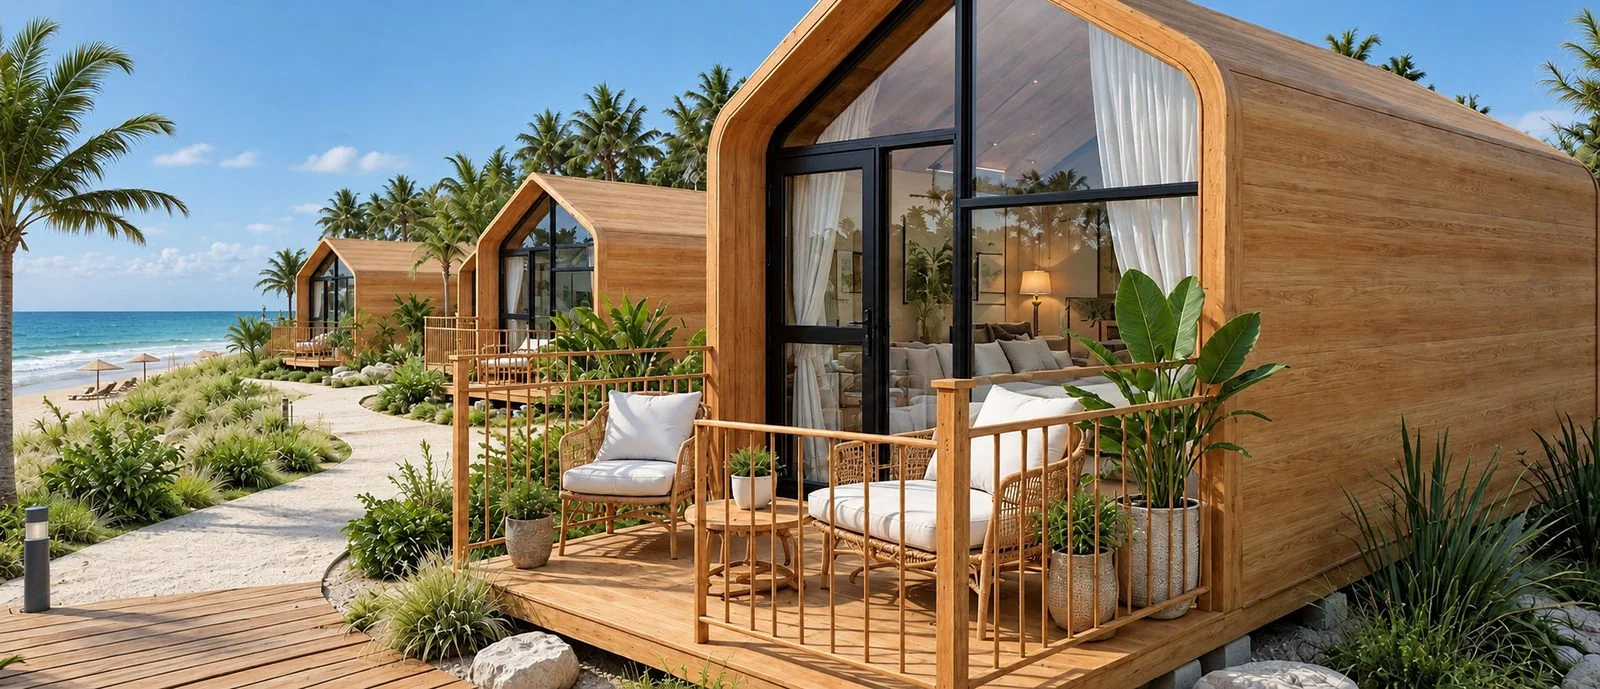
Spaces for relaxation and socialising.
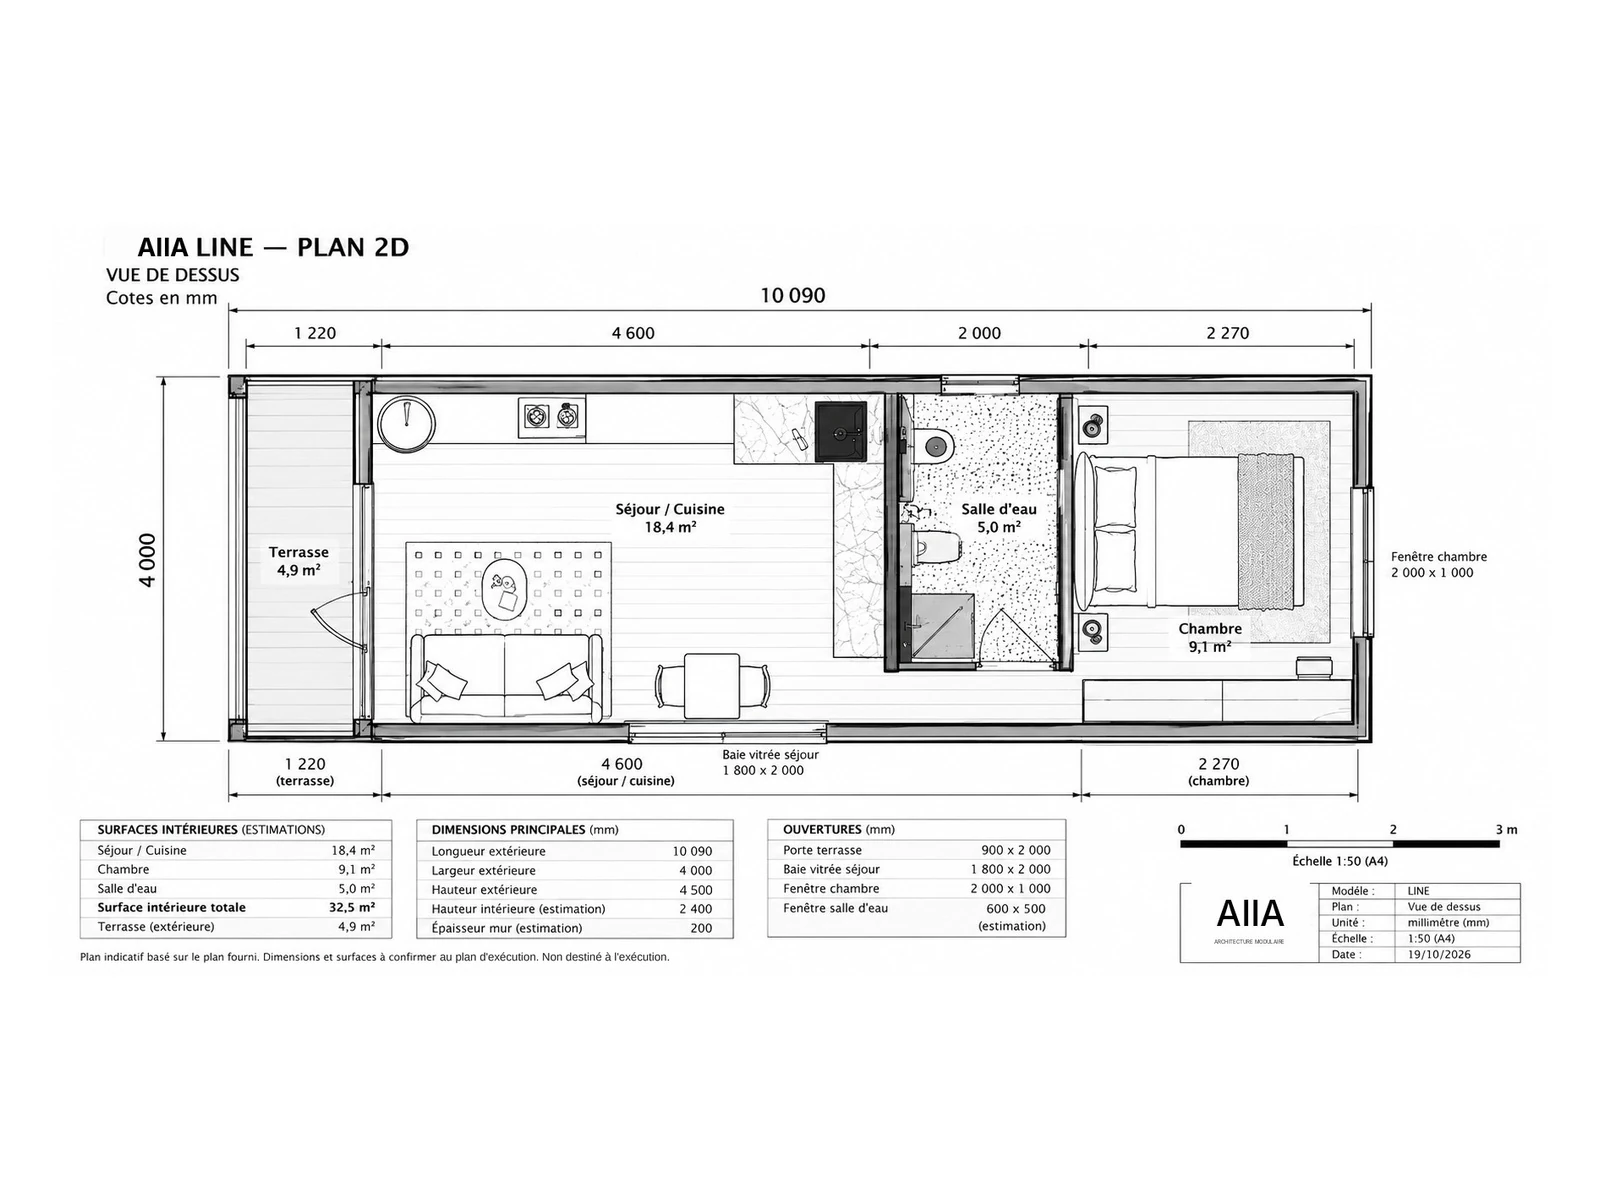
Integrate modular homes into your real estate developments or architecture projects.
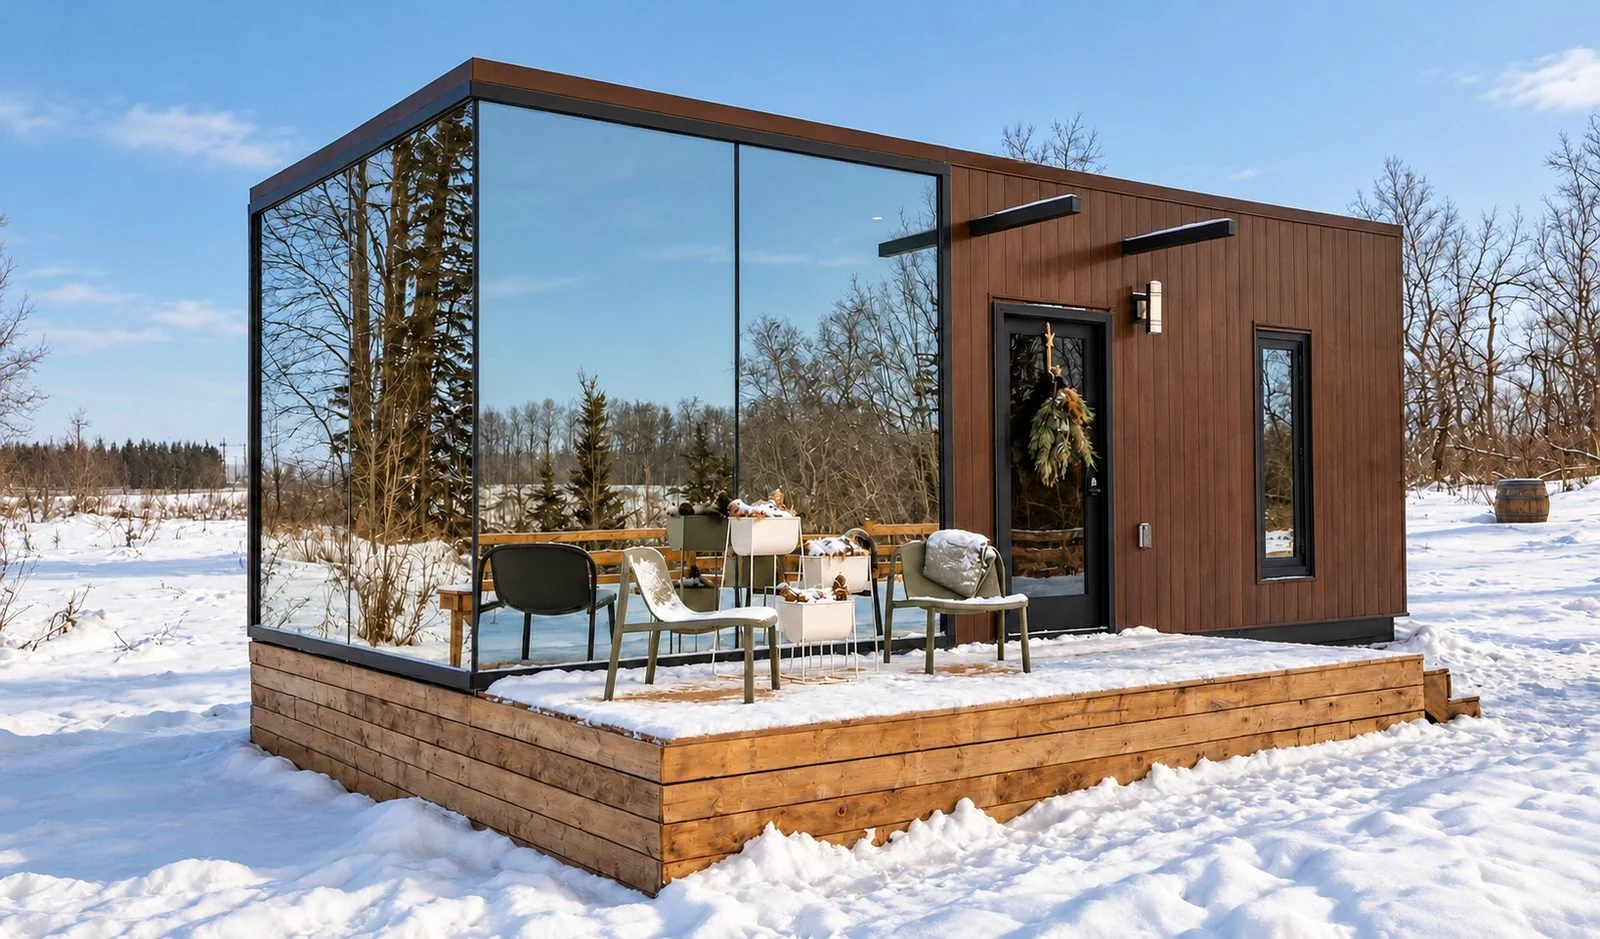
Equipped establishments, presented with their consent.
5-year lease, new units after 3 years: choose a model, then estimate your nightly rate and occupancy rate. Results after tax.
Estimate it for your local market.
Indicative default values: replace them with those of your financing offer.
Estimated annual rental income
Scale: €0 to € per month
Indicative seasonality: 2025 hotel nights by quarter and area (INSEE).
Leasing: 60 monthly payments excluding VAT, calculated on the value of the units with the rate and residual value entered. Default values: a rate of 3.71%, the average rate on new loans to SMEs in August 2026 (Banque de France), to be treated as a floor, since leasing generally costs more than a bank loan (CCI Paris Île-de-France); a residual value of 1%, the low end of the 1% to 6% of the price excluding VAT generally applied in equipment leasing (CCI Paris Île-de-France, June 2026). Actual terms depend on the financing offer. Renewal: after 3 years, AIIA replaces the units with new models; terms set out in the contract.
Costs estimated at 30% of rental income (platform fees, cleaning, maintenance, insurance), an indicative assumption to adjust.
Seasonality: 2025 hotel nights by quarter and area (INSEE, Informations rapides no. 123, 203, 286 and 39), spread across months by number of days. “Countryside” corresponds to INSEE's “outside coast and mountains” area, cities included. The occupancy rate entered is the annual average.
Tax: first year, lease payments deducted from the result. Company subject to IS: 15% up to €42,500 of profit, 25% above (2026 Finance Act, entreprendre.service-public.gouv.fr); the 15% rate requires turnover below €10M and fully paid-up capital, at least 75% held by individuals. A negative result gives rise to no tax. Sole trader: result × your marginal rate, excluding the owner's social security contributions. Other costs specific to your business are not included.
** Amounts excluding VAT. A VAT-registered business can in principle recover the VAT charged on lease payments. To be checked with your accountant.
Indicative simulation, for illustration only. It is neither investment advice, nor tax advice, nor a financing offer.